Understanding Property Insurance in Porter Ranch: A California Homeowner’s Guide
What does every Porter Ranch homeowner need to know about property insurance in California right now?
California homeowners insurance premiums have risen 84% since late 2020, according to Stanford research as of March 2026, and Porter Ranch’s location along the Santa Susana Mountain foothills makes understanding your coverage more critical than ever.
Why Property Insurance in Porter Ranch Matters Right Now
If you own a home in Porter Ranch, you are sitting on one of the most valuable residential assets in the San Fernando Valley. As of mid-2026, the median sale price here is approximately $1,262,000 with year-over-year appreciation of 3.3%, per MLS data. Homes range from roughly $431,000 for older condos up to $3.7 million for luxury estates behind the gates in communities like Westcliffe and The Ridges.
That is a lot of value to protect, and protecting it has gotten significantly harder. Seven of California’s twelve largest homeowners insurers have limited new policies or withdrawn from renewing existing ones since 2022, according to California Department of Insurance data. Approximately 400,000 California policies have been cancelled statewide since 2021.
What does that actually mean for you? It means that the insurance line item on your monthly housing statement is no longer something you can set and forget. With over 21 years of experience and more than 500 closed transactions across the San Fernando Valley, I have watched this issue move from a background concern to one of the most important factors in every Porter Ranch real estate decision I help clients navigate.
How California’s Insurance Crisis Directly Affects Porter Ranch Homeowners
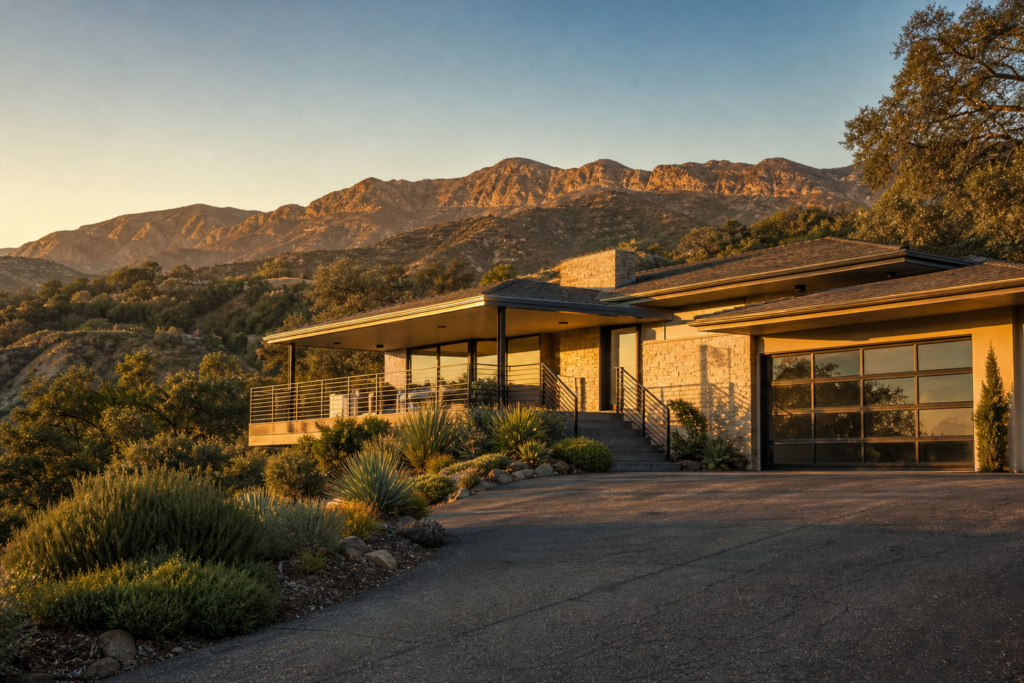
You might wonder why Porter Ranch, specifically, faces heightened insurance pressure. The answer is geography. Porter Ranch sits in the wildland-urban interface zone at the base of the Santa Susana Mountains. Those beautiful views from Sesnon Boulevard and the upper hillside neighborhoods come with proximity to open canyons and hillsides that insurers classify as elevated fire risk.
According to Insurify’s July 2026 report, California homeowners could see insurance rates increase 16% on average by the end of 2026, making California’s premium hikes the nation’s steepest this year at four times the 4% increase facing a typical American homeowner.
For context, consider that the 2025 Palisades and Eaton wildfires caused approximately $41 billion in insured losses for Los Angeles alone, per industry reports, making them the costliest U.S. wildfires ever recorded. Those fires changed the risk calculus for every insurer operating in Southern California.
Here is what I tell my clients when they are looking at homes near the upper reaches of Porter Ranch Drive or along the gated communities off Sesnon Boulevard: you must verify insurability before you fall in love with a property. The views from The Summit are breathtaking. The insurance quote might take your breath away, too, but for a very different reason.
What Carriers Are Doing in 2026
- State Farm received approval for a 17% emergency interim rate increase for homeowners policies as of March 2026, with an extended moratorium on non-renewals and cancellations for at least one additional year, per the California Department of Insurance
- Mercury Insurance received approval for a 6.9% average homeowners rate increase effective July 2026, impacting more than 650,000 California policyholders, per the California Department of Insurance’s December 2025 approval
- Statewide, State Farm has paid $1.26 for every $1 in premiums collected over the past nine years, resulting in $5 billion in cumulative losses, according to company filings
Standard Insurance vs. the FAIR Plan: What Porter Ranch Homeowners Need to Know
If your standard carrier has non-renewed your policy or you are shopping for coverage on a new purchase, you need to understand the difference between standard homeowners insurance and the California FAIR Plan.
The FAIR Plan is the state’s insurer of last resort. Enrollment has risen 230% since 2022, reaching roughly 668,000 policies covering about $724 billion in property exposure by early 2026, according to state data. As of March 2026, the FAIR Plan covers about 5% of California’s single-family homes, up from 1.5% in December 2020.
Key Coverage Differences
- Standard policy covers: Fire damage, wind and hail, lightning, theft, water damage from burst pipes, personal liability, and loss of use
- FAIR Plan covers: Fire damage, wind and hail, and lightning only
- FAIR Plan does NOT cover: Theft, water damage, personal liability, or loss of use, and dwelling coverage is capped at $3 million
In April 2026, the California Department of Insurance approved a 29.1% FAIR Plan rate increase, effective October 15, 2026. The FAIR Plan had originally requested 35.8%.
For a home valued at $1 million or more in a high-risk fire zone, combined FAIR Plan plus DIC (Difference in Conditions) cost estimates run $8,500 to $15,500 or more per year, before earthquake coverage, per industry estimates. That is a significant jump from what many Porter Ranch homeowners have been accustomed to paying.
If you are on the FAIR Plan, you should always supplement with a DIC policy to close those critical coverage gaps. I always encourage my clients to work with an insurance broker who specializes in high-value properties, because the gap between being properly covered and being dangerously exposed is wider than most people realize.
How Insurance Costs Impact Buying and Selling Homes in Porter Ranch
This is where my day-to-day experience in Porter Ranch intersects directly with the insurance conversation. Because I have worked this area consistently, helping clients navigate everything from luxury estates to new construction homes by builders like Toll Brothers, I see the insurance factor play out in real transactions.
Every California mortgage requires hazard insurance at funding. If you cannot secure coverage from a standard carrier and the FAIR Plan will not cover the property at replacement cost, the lender cannot fund the loan. Transactions have occurred where buyers had to walk away from accepted offers because no insurer would write a policy, according to industry reports.
Here are the most common scenarios I see causing problems:
- Scenario one: A buyer assumes insurance will be available, does not check until 14 days before closing, and the deal collapses
- Scenario two: Insurance comes back at $8,000 to $15,000 or more annually instead of the assumed $1,500 to $3,000, pushing PITI past qualification ratios and causing loan denial
What do I tell every buyer I work with in Porter Ranch? Start your insurance shopping the same week you get your offer accepted. Do not wait. Contact at least three insurance brokers, and specifically ask about wildland-urban interface classifications for the property’s exact location.
On the listing side, I focus on positioning homes the right way from the start. That includes helping sellers gather documentation about fire-hardening improvements and defensible space maintenance, and any upgrades that could improve a buyer’s insurance outcome. These details directly affect how quickly your home moves and at what price.
New California Consumer Protections You Should Know About
California is not standing still on this issue. Nine new consumer protection laws went into effect on January 1, 2026, addressing wildfire safety grants, expanded insurance discounts, and faster claim payouts.
Key Protections for Porter Ranch Homeowners
- Higher advance claim payments: Insurers must now pay 60% of contents limits, up to $350,000, as advance payments after wildfires, as of January 2026
- Fire-hardening incentives: A package of laws signed by Governor Newsom in October 2025 expanded grants for home fireproofing
- Non-renewal moratoriums: California law imposes a one-year moratorium on non-renewals in ZIP codes affected by a declared wildfire disaster
- Renewal protections: Homes meeting fire-hardening standards under SB 1076 receive renewal protections with 75-day notice requirements
- Carrier obligations: New rules issued by the California Department of Insurance in January 2026 require carriers receiving rate increases to also write more policies in high-risk areas
Additionally, the “Make It FAIR Act” was introduced in early 2026 to overhaul the FAIR Plan’s governance, claims handling, and transparency after regulators found it had failed to comply with 17 critical recommendations.
The combination of higher premiums plus more coverage availability should slowly stabilize the market through 2026 and 2027, per regulatory projections, but premiums are not expected to come back down. Plan on 25% to 50% higher insurance costs compared to your 2022 baseline.
Practical Steps to Protect Your Porter Ranch Home and Your Coverage
With a median household income near $148,000, per Census data, Porter Ranch homeowners have resources, but nobody wants to overpay or be underprotected. Here is what I recommend based on working with buyers and sellers across every pocket of this community.
Fire-Harden Your Property
Homes meeting fire-hardening standards under SB 1076 receive renewal protections. This includes fire-resistant roofing, ember-resistant vents, defensible space around the perimeter, and tempered glass windows. If you live along the hillside areas near Sesnon Boulevard or in the upper communities, these improvements are not optional anymore; they are essential. You can get prepared and learn about disaster resilience through official resources.
Shop Strategically and Early
By May 2026, regulators confirmed that six of California’s ten largest home insurance groups were committing to stay and grow in the state, alongside other companies adding coverage plans, per the California Department of Insurance. That means options are returning, but you need to be proactive. When you are ready to shop for homeowners insurance, make sure to contact multiple carriers.
Budget Realistically
Industry analysts project California homeowners insurance will experience continued 10% to 15% annual increases through 2029 as the market fully reprices risk, per industry projections. After the projected 16% increase in 2026, homeowners could face compounding increases totaling 35% to 50% over three years.
Verify Insurance Before Entering Escrow
Whether you are buying a new construction home or a resale property in one of Porter Ranch’s guard-gated communities, verify insurability before you are contractually committed.
Frequently Asked Questions About Property Insurance in Porter Ranch
Why are insurance rates rising so fast in Porter Ranch?
Porter Ranch sits in the wildland-urban interface zone near the Santa Susana Mountains, which places many homes in elevated fire-risk categories. According to Stanford research as of March 2026, average California homeowners insurance premiums rose 84% between late 2020 and March 2026. Porter Ranch’s geography and high home values compound this statewide trend.
What is the California FAIR Plan and do I need it?
The FAIR Plan is California’s insurer of last resort for homeowners who cannot obtain coverage through standard carriers. As of early 2026, enrollment has risen 230% since 2022 to roughly 668,000 policies. It covers fire, wind, hail, and lightning but excludes theft, water damage, liability, and loss of use. If you are on the FAIR Plan, you should supplement with a DIC policy.
How much does insurance cost for a typical Porter Ranch home?
For homes in high-risk fire zones valued at $1 million or more, combined FAIR Plan and DIC coverage estimates run $8,500 to $15,500 or more per year before earthquake coverage, per industry estimates. Standard carrier costs vary but have been rising significantly across the board.
Can my insurance company cancel my policy without warning?
California law requires specific notice periods. Homes meeting fire-hardening standards under SB 1076 receive renewal protections with 75-day notice requirements. Additionally, non-renewals are subject to a one-year moratorium in ZIP codes affected by a declared wildfire disaster.
What is a DIC policy and do I need one?
A Difference in Conditions policy supplements the FAIR Plan by covering what it excludes: theft, water damage, personal liability, and loss of use. If you are on the FAIR Plan, a DIC policy is strongly recommended to avoid dangerous coverage gaps on a home worth over $1 million.
How does insurance affect my ability to get a mortgage in Porter Ranch?
Every California mortgage requires hazard insurance at funding. If insurance costs come in significantly higher than expected, your PITI ratio may exceed qualification limits, potentially causing loan denial. Always start insurance shopping immediately after your offer is accepted.
What can I do to lower my insurance premiums?
Fire-harden your home with fire-resistant roofing, ember-resistant vents, defensible space, and tempered glass. These improvements may qualify you for discounts under new 2026 consumer protection laws and help maintain coverage with standard carriers.
Are new construction homes in Porter Ranch easier to insure?
Newer construction homes, including those by builders like Toll Brothers, typically incorporate current fire-safety building codes, which can make them more attractive to insurers compared to older resale properties that may need retrofitting.
What new laws protect California homeowners in 2026?
Nine consumer protection laws took effect January 1, 2026, including expanded fire-hardening grants, higher advance claim payments after wildfires (60% of contents limits up to $350,000), and requirements that carriers receiving rate increases must write more policies in high-risk areas.
Should I check insurance availability before buying a home in Porter Ranch?
Absolutely. This is one of the most important steps in any Porter Ranch home purchase in 2026. Contact multiple insurance brokers the same week your offer is accepted. Do not wait until two weeks before closing, as that is how deals fall apart.
The Bottom Line on Property Insurance for Porter Ranch Homeowners
Property insurance in California is no longer a background detail. It is a front-and-center financial decision that affects your monthly costs, your ability to secure a mortgage, and the long-term value of your Porter Ranch home. With over 21 years of experience, more than 500 closed transactions, and a 5.0 average rating across 103 client reviews, I have built my practice on giving my clients the kind of honest, strategic guidance that keeps surprises out of the equation. If you are buying, selling, or simply trying to make sense of your insurance options in Porter Ranch, I am here to help you think through every angle. Reach out to me, Scott Himelstein, at 818-396-3311. For me, Porter Ranch is not just another market. It is an area where I have built long-term relationships and a deep understanding of how to get results for my clients.
Work with Scott