Is Los Angeles Luxury Real Estate Becoming Too Expensive? Mansion Tax, Wealth Taxes, and the California Luxury Flight
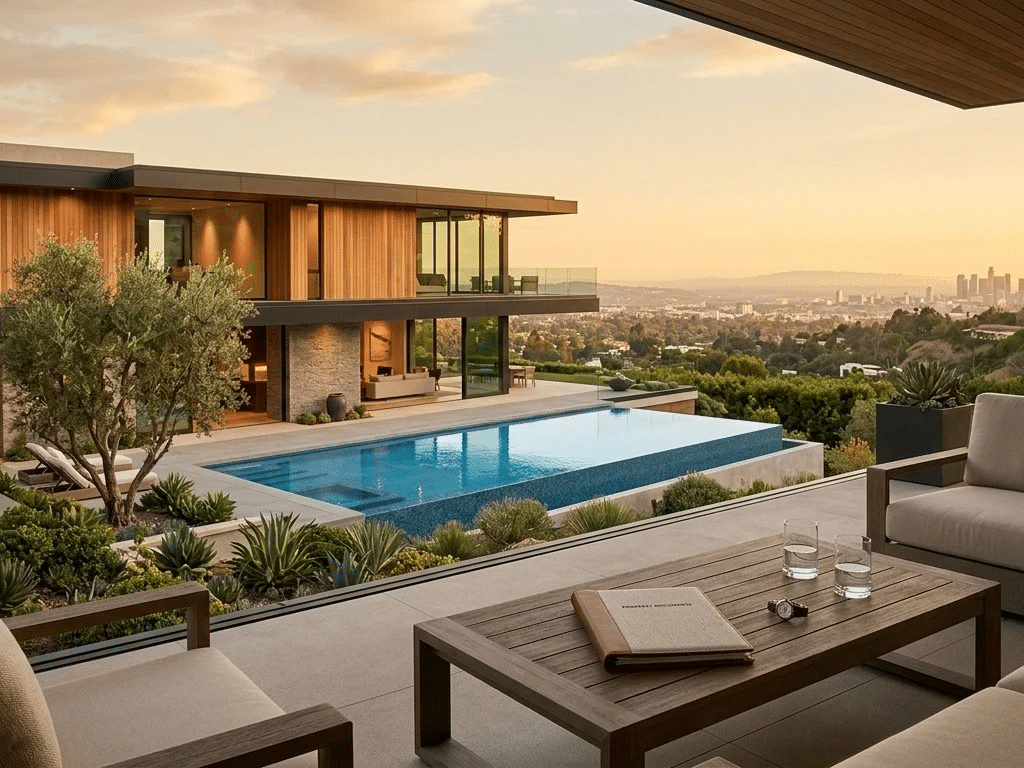
For homeowners with multimillion-dollar properties in Los Angeles, deciding whether to stay, sell, or relocate has become a more complicated financial decision. Beyond a home’s market value, sellers may need to consider transfer taxes, capital gains, insurance costs, ongoing property expenses, and the tax implications of moving to another state.
These questions are especially relevant for owners of luxury homes in Beverly Hills, Bel Air, Brentwood, Hidden Hills, Malibu, and Porter Ranch. While Southern California continues to offer desirable neighborhoods, strong lifestyle appeal, and access to major business and entertainment industries, some high-net-worth homeowners are taking a closer look at the long-term cost of owning property here.
Scott Himmelstein of the Scott Himmelstein Group explores these concerns in his discussion of Los Angeles luxury real estate, including the city’s Measure ULA transfer tax, California’s proposed billionaire tax, and the financial considerations behind relocating to states such as Texas, Nevada, and Florida.
Why Luxury Homeowners Are Rethinking Their Real Estate Decisions
Los Angeles remains an internationally recognized luxury real estate market. Its climate, beaches, restaurants, private schools, entertainment industry, and professional networks continue to attract buyers from across the country and around the world.
However, owning a luxury property involves more than paying the mortgage or maintaining the home. Owners must also consider property taxes, homeowners insurance, maintenance, utilities, and the costs associated with eventually selling.
For someone who owns a property worth $7 million, $10 million, or $20 million, even a small percentage difference in transaction costs can translate into hundreds of thousands of dollars.
That is why some homeowners are asking a different question: How much equity will they actually keep if they sell?
The answer depends on the property, its purchase price and adjusted tax basis, the length of ownership, the selling costs, and the owner’s individual tax situation. For some homeowners, the financial implications are significant enough to influence whether they sell now, hold the property longer, rent it out, or consider relocating.
How Los Angeles Measure ULA Affects Luxury Home Sales
Measure ULA, often called the mansion tax, adds a special transfer tax to qualifying real estate transactions within the City of Los Angeles. The tax is charged based on the value of the property conveyed, rather than the seller’s profit.
As of July 1, 2026, the city’s adjusted thresholds are:
- More than $5.4 million but less than $10.9 million: A 4% Measure ULA tax.
- $10.9 million or more: A 5.5% Measure ULA tax.
These rates are in addition to the city’s standard real property transfer tax. The applicable thresholds and rates should be verified with the City of Los Angeles before a transaction closes. Properties elsewhere in Los Angeles County may be subject to different local transfer-tax rules. Source: City of Los Angeles Office of Finance.
What does that mean for a multimillion-dollar sale?
Consider a hypothetical Los Angeles property selling for $10 million. Under the thresholds effective July 1, 2026, that sale falls into the 4% Measure ULA tier because it is below $10.9 million.
The Measure ULA portion would be approximately $400,000. Adding the city’s standard 0.45% transfer tax brings the combined city transfer taxes to approximately $445,000, before other closing costs.
Now consider a property selling for $12 million. At the 5.5% Measure ULA rate, the special tax would be $660,000. Including the standard city transfer tax, the combined city transfer taxes would be approximately $714,000.
These examples illustrate why transfer taxes can materially affect a seller’s net proceeds. They do not include agent commissions, escrow and title charges, loan payoffs, or any applicable income taxes.
The important distinction is that Measure ULA is based on the transaction value, not the seller’s capital gain. A seller’s actual profit may be much smaller than the sale price, but the transfer tax is still calculated under the applicable rules.
How transfer taxes can influence buyer and seller behavior
A large selling expense can affect how homeowners approach their next move. Some may delay listing, compare the cost of selling with the cost of holding the property, or explore renting instead.
Buyers may also factor anticipated future selling costs into their investment calculations. That does not mean every luxury property will lose value or become difficult to sell. It does mean transaction expenses deserve a place in the financial analysis before an owner makes a major decision.
California’s Billionaire Tax Proposal: What Homeowners Should Know
Another source of uncertainty is California’s proposed billionaire tax.
As of October 2026, Proposition 40 is on the November 3, 2026, statewide ballot. The measure proposes a one-time tax of 5% on the net worth of certain billionaires who were California residents on January 1, 2026. Its covered assets include certain businesses, securities, art, collectibles, and intellectual property, while real estate and some retirement assets are excluded. The proposal is not an enacted annual wealth tax. Sources: California Legislative Analyst’s Office, California Secretary of State voter guide.
This distinction matters. The proposal is directed at qualifying taxpayers with assets above the specified threshold, not at every luxury homeowner or every California resident with substantial wealth.
Nevertheless, the debate has brought renewed attention to how tax policy may influence decisions among entrepreneurs, investors, and other high-net-worth individuals. People whose wealth is concentrated in investments or private businesses may be particularly sensitive to changes in tax exposure, liquidity, and long-term planning.
Because Proposition 40 is a ballot measure, its outcome and any subsequent legal or administrative developments should be confirmed before anyone makes financial decisions based on it.
Why Some Affluent Californians Consider Texas, Nevada, and Florida
For homeowners and business owners who can relocate, states such as Texas, Nevada, and Florida may offer a different tax structure. Texas, Nevada, and Florida do not impose a state individual income tax, which can be an important consideration for some high earners.
However, a move should not be evaluated on income tax alone. Home prices, property taxes, insurance premiums, maintenance, travel, business needs, and family circumstances can change the overall calculation.
A buyer comparing a luxury property in Los Angeles with one in Austin or Las Vegas should look at the complete cost of ownership rather than assuming that one location will automatically be cheaper.
The decision may also involve lifestyle. Some owners value Southern California’s climate, professional connections, and proximity to family. Others may be able to work remotely, operate a business elsewhere, or use a relocation as an opportunity to purchase a larger property.
There is no single answer for every homeowner. The right choice depends on the person’s priorities, finances, and circumstances.
Moving Out of California Does Not Automatically End California Tax Obligations
A change of address alone does not necessarily establish that someone is no longer a California tax resident.
Residency and domicile determinations can depend on multiple factors, including where a person maintains their home, where their family lives, the location of business and personal connections, and the overall pattern of their time and activities.
Spending more than half the year outside California does not automatically settle every residency question. The number of days spent in a state can matter, but it is not the only consideration.
Anyone considering a move primarily for tax reasons should consult a qualified tax professional familiar with California residency rules before changing their arrangements. A tax attorney or CPA can help evaluate the individual’s circumstances and identify the records and steps that may be relevant.
This is particularly important for business owners, investors, and people anticipating a major property sale or other financial event.
Comparing a $10 Million Los Angeles Property Sale With Texas
A comparison between Los Angeles and Texas can help illustrate why sellers look beyond a property’s headline price. However, the outcome depends on the specific transaction.
For a $10 million property within the City of Los Angeles, the current Measure ULA tier is 4%, not 5.5%, because the sale price is below the $10.9 million threshold effective July 1, 2026. With the standard city transfer tax added, the combined city transfer-tax amount would be approximately $445,000.
Texas does not have an equivalent statewide individual income tax or a comparable Los Angeles Measure ULA tax. Nevertheless, a Texas seller still needs to account for ordinary transaction expenses and any applicable federal tax obligations.
The capital gains tax calculation is not based on sale price alone. It can depend on the property’s adjusted basis, eligible improvements, ownership and use, depreciation, and whether an exclusion applies. Investment properties may have different tax consequences from primary residences.
For these reasons, a claim that selling in Texas will always save a particular amount would be misleading. A meaningful comparison should use the actual property’s numbers, the owner’s tax situation, and realistic estimates of all selling expenses.
What This Could Mean for Los Angeles Luxury Real Estate
The luxury market is influenced by more than tax policy. Interest rates, inventory, buyer demand, employment trends, economic confidence, and the appeal of individual neighborhoods all affect market conditions.
Additional selling expenses may influence how some owners price their homes or decide when to list. Policy uncertainty may also encourage some affluent households to review their financial plans.
However, the existence of these pressures does not establish that Los Angeles luxury real estate is collapsing or that all wealthy homeowners are leaving California. The region continues to attract buyers who value its lifestyle, businesses, and globally recognized neighborhoods.
For homeowners, the practical lesson is to understand the full financial picture before making a decision. That means reviewing likely selling costs, evaluating the property’s current market value, considering the cost of holding it, and obtaining professional tax advice when needed.
Planning Your Next Move in the Los Angeles Luxury Market
If you own a high-value property in Los Angeles, deciding whether to sell, hold, rent, or relocate deserves careful analysis. The right approach begins with understanding your equity, estimating transaction expenses, and comparing realistic alternatives.
Scott Himmelstein and the Scott Himmelstein Group help clients navigate the Southern California real estate market with an emphasis on local insight and informed decision-making.
Watch the Video
Watch Scott’s full discussion of the Los Angeles luxury real estate market, Measure ULA, California’s billionaire tax proposal, and the considerations behind relocating to other states. The video walks through hypothetical luxury home-sale scenarios and explains why understanding your potential costs is an important part of planning your next move.
If you’re considering selling a luxury property or want to understand what your home may be worth in today’s market, reach out to Scott Himmelstein and the Scott Himmelstein Group for a property-specific discussion.
Work with Scott