Selling a Home in Los Angeles in 2026: 7 Strategies to Attract Buyers and Protect Your Equity
Selling a home in Los Angeles in 2026 requires more than choosing a listing price and putting a sign in the yard. Mortgage rates, insurance costs, renovation expenses, and changing buyer priorities all influence how sellers should prepare for the market.
For homeowners across Los Angeles County, the key is understanding what buyers value today and positioning a property accordingly. Some sellers may benefit from highlighting energy efficiency or an assumable mortgage. Others may need to address repairs, explore buyer financing incentives, or plan their next move before listing.
Scott Himmelstein of the Scott Himmelstein Group shares his perspective after more than two decades in Los Angeles real estate, outlining practical strategies sellers can consider to prepare their homes, protect their equity, and make informed decisions.
Understanding the Los Angeles Housing Market in 2026
The Los Angeles housing market faces several competing forces. Higher borrowing costs can make monthly payments more expensive for buyers, while insurance premiums, property taxes, and maintenance costs can affect the overall affordability of homeownership.
Mortgage rates have also remained a major consideration for buyers. In October 2026, the average U.S. 30-year fixed mortgage rate reached 7.40%, according to Freddie Mac data reported by Reuters. That national figure is not a specific Los Angeles rate, but it illustrates the financing pressure many buyers face. <Link url=”https://www.reuters.com/markets/us/us-30-year-fixed-mortgage-rate-jumps-740-2026-10-08/” title=”Read the October 2026 mortgage-rate report”/>.
For sellers, this means buyers may pay closer attention to monthly expenses, property condition, and the long-term cost of owning a home. A property that is well-prepared, accurately priced, and marketed around its strongest features may be better positioned to compete.
Scott also emphasizes that real estate conditions vary from neighborhood to neighborhood. A citywide estimate or automated valuation cannot fully account for a home’s condition, layout, location, and the most relevant comparable sales.
Before deciding on a listing price, homeowners should review recent sales, competing listings, and the specific conditions affecting their neighborhood.
Strategy 1: Find Out Whether Your Mortgage Is Assumable
If you have a low-interest mortgage, it may be worth investigating whether a qualified buyer can assume your existing loan.
Some FHA and VA loans may be assumable, subject to program requirements, lender or servicer approval, and other conditions. Conventional mortgages generally have different restrictions, so homeowners should never assume their loan can be transferred.
Why does this matter? A buyer financing a home at today’s higher rates may be interested in a property with an eligible mortgage carrying a substantially lower rate.
An assumable loan could provide a financing advantage, but there are important details to consider. Buyers may need to cover the difference between the outstanding loan balance and the purchase price, and the assumption must meet the applicable requirements.
What sellers can do: Contact your mortgage servicer to ask whether your loan is assumable and what the process involves. If it is eligible, discuss how to present the feature accurately in your listing marketing.
A low-rate mortgage is not automatically a guarantee of a higher sale price, but it may be a useful point of differentiation for the right buyer.
Strategy 2: Make Energy Efficiency Part of Your Home’s Appeal
With housing expenses under close scrutiny, energy-efficient features can help sellers communicate the potential benefits of owning their property.
If your home has solar panels, upgraded insulation, energy-efficient windows, a smart thermostat, or other efficiency improvements, make sure those features are documented and included in the marketing when appropriate.
Owned solar systems and leased solar systems should be described accurately because the ownership structure and any remaining contractual obligations may affect a buyer’s decision.
Utility bills can also help illustrate the home’s operating costs. Where practical, provide accurate historical information and explain any relevant factors that could affect future expenses.
Rather than focusing only on square footage and finishes, sellers can show buyers how the home’s features may contribute to everyday comfort and household budgeting.
What sellers can do: Gather records for energy upgrades, warranties, solar agreements, and utility expenses before listing. Clear documentation gives prospective buyers more information to evaluate the property.
Strategy 3: Consider a Pre-Listing Home Inspection
Unexpected repairs can complicate a real estate transaction. A roof issue, plumbing concern, or heating and cooling problem discovered during the buyer’s inspection may lead to additional negotiations, repair requests, or delays.
A pre-listing inspection gives sellers an opportunity to identify potential concerns before the home goes on the market.
Once the findings are available, sellers can decide which repairs make financial sense, whether to obtain contractor estimates, or whether to disclose an issue and price the property accordingly.
A pre-listing inspection does not eliminate the need for required disclosures or guarantee that a buyer’s inspection will uncover nothing new. Its value is in helping the seller prepare with more information.
This can be particularly useful for homeowners considering an as-is sale. Selling as-is does not necessarily remove disclosure obligations or prevent a buyer from conducting inspections.
What sellers can do: Discuss the inspection process with your real estate professional, select a qualified inspector, and review the findings before deciding how to proceed.
Being prepared can help reduce avoidable surprises and make negotiations more straightforward.
Strategy 4: Explore a 2-1 Mortgage Rate Buydown
A seller does not always have to rely on a price reduction to make a home more attractive. In some transactions, a seller-funded mortgage rate buydown may be worth considering.
A temporary 2-1 buydown is a financing arrangement designed to reduce a buyer’s effective interest rate by two percentage points in the first year and one percentage point in the second year, before the loan returns to its regular rate for the remaining term.
The specific structure, eligibility, cost, and lender requirements need to be confirmed for each transaction.
For example, a seller might consider contributing toward an eligible buyer’s financing costs instead of reducing the asking price by the same amount. Whether that is the better option depends on the buyer’s needs, the seller’s net proceeds, the loan terms, and the property’s market position.
A buydown does not permanently lower the mortgage rate, so buyers must be comfortable with the payment after the temporary benefit expires.
What sellers can do: Ask the buyer’s lender to explain the available buydown options and provide a written cost comparison. Compare the proposed concession with a direct price reduction before deciding which approach makes financial sense.
Strategy 5: Highlight Potential Accessory Dwelling Unit Income
An accessory dwelling unit, commonly called an ADU, is a secondary home on a residential property. Depending on the layout and applicable regulations, it may be attached to the primary house, detached in the backyard, or created from an existing space such as a garage.
For some Los Angeles properties, an existing ADU or the potential to build one can be an important selling point.
A second unit may offer flexibility for extended family, guest accommodations, or rental income. However, the property’s zoning, lot conditions, permitting requirements, construction costs, and local rules all matter.
California’s Department of Housing and Community Development provides an updated ADU handbook covering state law, including changes that took effect in 2026. Homeowners can use it as a starting point for understanding the rules, although local requirements and the details of a particular property must also be reviewed. <Link url=”https://www.hcd.ca.gov/building-standards/adu/handbook” title=”Read California’s ADU Handbook”/>.
Sellers should avoid promising that an additional unit can be built or that it will generate a particular amount of rent without supporting evidence.
What sellers can do: Gather existing permits and plans, confirm the status of any current secondary unit, and consult the appropriate local planning or building department before advertising future development possibilities.
When documented properly, an existing ADU or a realistic development opportunity can help buyers see more ways to use a property.
Strategy 6: Invest in Staging, Photography, and Listing Presentation
Most buyers begin their home search online, making the quality of a property’s listing presentation especially important.
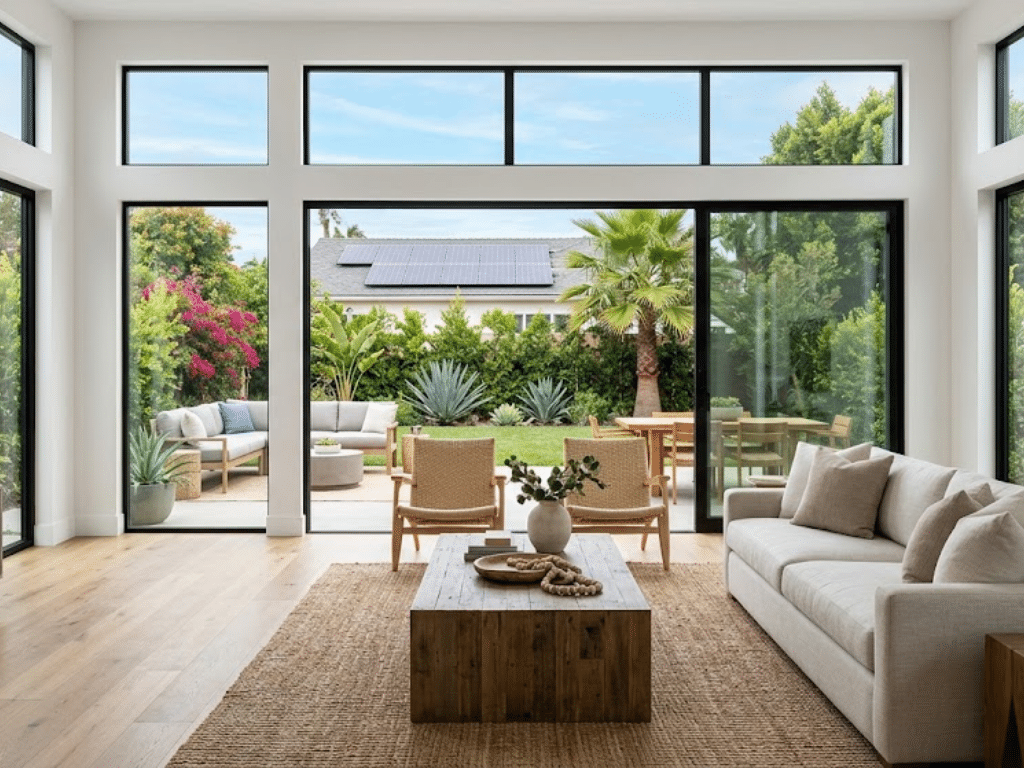
Professional photography, thoughtful staging, clean spaces, and good lighting can help buyers understand the layout and appreciate a home’s features before they schedule a showing.
Scott recommends preparing listings with digital presentation in mind. Although no seller can guarantee that a particular property will receive preferential placement in every search or recommendation system, clear photographs and accurate listing information can help people evaluate the home.
Before the photography session, consider decluttering, removing distracting personal items, improving lighting, and addressing visible maintenance issues. Staging can help define how rooms function, especially when a property is vacant or has an unusual layout.
Marketing should also emphasize the features most relevant to likely buyers, whether that means outdoor living areas, mature landscaping, flexible spaces, energy upgrades, or proximity to local amenities.
What sellers can do: Build a preparation timeline that includes cleaning, repairs, staging, photography, and a coordinated marketing plan. The goal is to present the home’s genuine strengths clearly and consistently.
Strategy 7: Protect Your Equity When Evaluating Off-Market Offers
Many homeowners receive unsolicited letters, postcards, calls, or text messages from investors interested in buying their properties.
Some of these offers may be legitimate, but an unsolicited cash offer should not automatically be treated as the property’s full market value.
An investor may be looking for a quick transaction, a particular property type, or an opportunity to purchase without competing against other buyers. In exchange for speed or convenience, the offer may differ from what the property could receive through broader market exposure.
That does not mean every off-market offer is a bad option. A direct sale may suit an owner who values a simpler process, has a tight timeline, or does not want to prepare the property for a conventional listing.
The important point is to understand the trade-offs before signing an agreement.
What sellers can do:
- Compare the offer with recent comparable sales and current competition.
- Review the proposed purchase price alongside fees, repair costs, contingencies, and closing terms.
- Understand any cancellation rights, deadlines, or contractual obligations.
- Consider obtaining independent legal advice when the agreement is complex or unfamiliar.
- Evaluate whether convenience and speed justify any difference in expected proceeds.
Knowing the likely market value of your home gives you a stronger basis for deciding whether an off-market offer meets your goals.
Planning Your Next Move: Could a Bridge Loan Help?
One challenge homeowners face is deciding where to live between selling their current property and purchasing the next one.
Some sellers worry about buying a new home before their existing property sells. Others do not want to make a contingent offer, move twice, or temporarily relocate while waiting for their transaction to close.
A bridge loan may be one option to explore. Depending on the lender and loan structure, it can provide short-term financing that helps a homeowner access equity or cover expenses associated with purchasing another property before selling the current one.
The potential advantage is flexibility. A homeowner may be able to purchase the next property first, move, and then prepare the original home for listing without living through showings and staging.
However, bridge loans can involve significant costs, eligibility requirements, and repayment risks. Owners may temporarily carry expenses associated with two properties, and there is no guarantee the existing home will sell at the anticipated price or within the expected timeframe.
What sellers can do: Speak with a qualified lender before making plans. Request a detailed estimate of fees, interest, payment obligations, qualification requirements, and what happens if the current home takes longer to sell.
Compare the bridge-loan approach with alternatives such as a sale contingency, a negotiated rent-back arrangement, or timing both transactions together. The right choice depends on the homeowner’s financial situation and tolerance for risk.
Is a New Group of Buyers Returning to Los Angeles?
Scott also points to a trend he says he is observing among some clients: buyers who previously relocated to Sunbelt cities are considering a return to Southern California.
Cities such as Phoenix, Las Vegas, Austin, Dallas, and Nashville attracted people seeking different housing costs, lifestyles, or work arrangements during the pandemic years. Scott believes some former Los Angeles residents are now reassessing those moves and looking for the features they valued in Southern California.
For sellers, the potential lesson is to think carefully about who might be attracted to their home and why.
A buyer considering a return to Los Angeles may prioritize usable outdoor space, established landscaping, a functional floor plan, schools, access to employment, or proximity to dining and recreation. Those priorities will vary by household and neighborhood.
This should be viewed as Scott’s market observation rather than proof of a broad, quantified migration trend. Sellers should work with current local data to understand which buyer groups are active in their area.
In communities such as Porter Ranch and across the San Fernando Valley, property-specific features and neighborhood amenities may be especially relevant to how a home is positioned.
What Sellers Should Do Before Setting a Listing Price
A thoughtful pricing decision begins with current, local information. National headlines and automated estimates can provide context, but they cannot replace an assessment of a property’s condition, location, features, and competition.
Before listing, homeowners should review:
- Recent comparable sales: Focus on properties that closely match the home in location, size, condition, and features.
- Active competition: Understand what buyers can choose from right now.
- Property condition: Identify repairs and presentation improvements that may affect buyer interest.
- Ownership costs: Gather information about insurance, utilities, maintenance, and any major ongoing expenses.
- Potential financing advantages: Determine whether an assumable mortgage or another legitimate selling feature applies.
- The next-home plan: Consider timing, financing, and temporary housing before committing to a sale date.
- Negotiation options: Decide in advance how you would evaluate repair requests, closing-cost assistance, or other concessions.
These steps can help sellers make decisions based on the actual property and market rather than fear or speculation.
Final Thoughts: A Strong Selling Strategy Starts Before the Listing
Selling a home in Los Angeles in 2026 does not require predicting every market change. It requires understanding your options, preparing your property, and building a strategy around the buyers who may realistically consider it.
An assumable mortgage, documented energy upgrades, a pre-listing inspection, a carefully evaluated rate buydown, or a permitted ADU may each offer advantages in the right situation. Professional presentation and a well-planned transition to your next home can also make the process easier to manage.
Not every strategy will suit every property. The best approach depends on your goals, your finances, your neighborhood, and the condition of your home.
Before deciding whether to sell, gather the information you need to compare your options. A clear plan can help you move forward with greater confidence.
Watch the Video
Want to hear Scott Himmelstein’s full breakdown of selling a home in Los Angeles in 2026?
Watch the video for his discussion of market conditions, seller strategies, assumable mortgages, energy efficiency, pre-listing inspections, mortgage buydowns, ADU potential, bridge loans, and the buyer trends he is watching across Southern California.
Disclaimer: This article is for general informational purposes only and is not financial, mortgage, tax, or legal advice. Mortgage assumptions, rate buydowns, bridge loans, and ADU development are subject to lender requirements, local regulations, costs, and individual circumstances. Verify current market data and consult qualified professionals before making financial or real estate decisions.
Work with Scott